
Yoann Ignatiew
General Partner, Head of International Equity and Diversified

General Partner, Head of International Equity and Diversified

Global Equities Portfolio Manager

General Partner, Head of Fixed Income
Equity markets reached new highs in the second quarter of the year. The S&P 500 posted a performance of +14.4% in Dollars at the end of June, while the Euro Stoxx 50 and the Nasdaq were up 14.4% and 12.5% respectively[1]. China is stalling, affected by a tightening of its monetary policy as well as a hardening tone from its Party seeking to assert its power on its 100th anniversary.
With regard to the pandemic, the vaccination rate is progressing with 24% of the world’s population inoculated with at least one dose of a Covid-19 vaccine[2] to date. This figure is rather promising, but one must be remember that only 1% of people in low-income countries have received at least one dose. In addition to the challenge of vaccinating the poorest countries, the emergence of several variants is driving new cases higher again, even in countries with high vaccination rates, such as Israel or the United Kingdom.
At the same time, the various stimulus packages put in place by governments continue to support the recovery. In the US, after long weeks of negotiations, Joe Biden appears to have reached a bipartisan agreement on his USD 1 trillion-plus infrastructure plan. Notably, the latter will not be financed by a tax increase, a condition rejected by the Republicans, but by stricter control of their collection. In Europe, the EUR 750 billion stimulus package will flow into the economies of the beneficiary member states starting in July. Although it took a year to come to a final agreement (which the member countries originally agreed on last July), it is now effective and should prove to be a strong support to the economic recovery of the Zone.
The central banks are still involved but seem to be gradually thinking of a normalisation. In China, which is ahead of the cycle, the PBC has already started tightening monetary policy. The Fed is continuing its balancing act between accommodative rhetoric and market concerns about inflation. The FOMC[3] let slip a more “hawkish[4]” tone at its last committee and is now counting on two rate hikes in 2023, according to the projections of its members (dot plot). Furthermore, inflation forecasts have been revised upwards and are expected to reach 3.4% by the end of 2021. The ECB remains the most accommodating central bank due as the zone continues to lag the previously mentioned regions. Christine Lagarde recently stated that a tightening of monetary policy would be premature and would pose a risk to the ongoing economic recovery and inflation outlook.
[1] Source: Bloomberg, 30/06/2021.
[2] ourworldindata, 30/06/2021.
[3] Federal Open Market Committee, an organ of the US Central Bank.
[4] Positioning in favour of a less accommodating monetary policy to fight inflation.
In this context, R-co Valor had a net equity exposure of 84% at the end of June. In the second quarter, the best contributors to performance were the mining and technology sectors. The former benefited from the boom in commodity prices and, in particular, from strong investor interest in copper. The lull in US rates gave the latter a breather during the period. In contrast, the leisure/services sector is the worst contributor, suffering from the resurgence of variants and possible new border closures.
In terms of portfolio movements, profit taking was carried out on cyclical stocks[1] that had rebounded particularly well during the quarter and since the beginning of the year. Partial sales were made, with some mining companies benefiting from a recovery in demand in the face of sometimes unstable production, as well as on energy stocks, with a relief on Canadian Natural Resources and the sale of Suncor. OPEC+[2], despite an increase in its production in stages, is leaving part of its reserves untapped for the moment. Also, the IBM line was entirely sold following the rebound of the stock. We trimmed ABB at the margin, following the publication of better than expected figures. On the buy side, the cautious stance of Chinese authorities and the tightening of the regulatory environment allowed us to tactically strengthen certain positions with solid fundamentals (Ping An, New Oriental Education, Kingsoft Cloud, etc.). We have also strengthened Airbus, as the stock seems particularly well positioned for the recovery. In addition, a new line belonging to the technology sector was introduced in the portfolio: (1) MercadoLibre, an e-commerce platform mainly present in Latin America, also offering payment and credit services that are particularly interesting in an area that has been underbanked until now. (2) Coinbase, a crypto-currency exchange platform, giving us exposure to the growing trading volume of these “new” assets and the opportunities associated with the emergence of decentralized finance solutions. The platform, which has 56 million users, offers services tailored to individuals as well as companies and financial institutions.
For the moment, we are keeping our exposure to cyclical stocks, while opportunistically trimming certain positions when we consider it appropriate. The fund is currently well positioned for a return of inflation, notably through its exposure to commodities. Our positioning on financial stocks also seems appropriate in a particularly favourable post-stress environment, supported by substantial share buyback announcements and significant dividend increases. Finally, our exposure to Europe, at a 10-year high, seems appropriate as the region should catch up in the coming months.
What can we expect for the rest of the year? Macroeconomic publications continue to generally positively surprise. The liquidity resulting from the various stimulus packages should not only flow to the targeted economies, but also to their trading partners more globally. From a microeconomic perspective, earnings expectations continue to be revised upwards with +50% expected in Europe and +35% in the US[3]. However, there is a shadow over inflation which, if it continues, could push the Fed to be less accommodating more quickly than the markets had anticipated. More than the evolution of commodity prices, the labor market and the rise in rents will be the data to follow in the United States in the coming months.
[1] Cyclical stocks are highly correlated to economic cycles. They therefore benefit greatly from periods of recovery and expansion but are also the first to be affected by an economic downturn.
[2] Organisation of Petroleum Exporting Countries plus its partner countries.
[3] JP Morgan, June 2021.
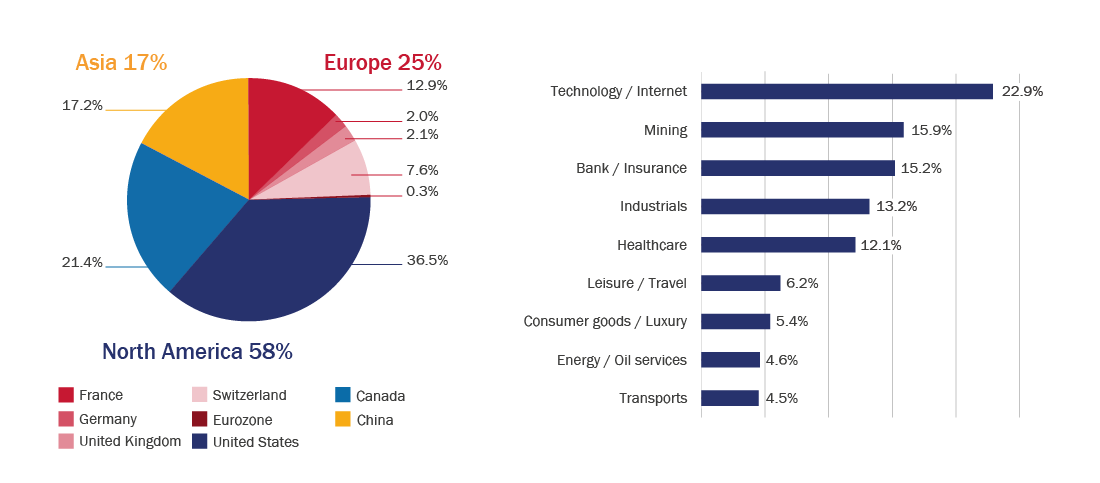
Source: Rothschild & Co Asset Management Europe, 30/06/2021.
The characteristics/objectives/strategies mentioned above are indicative and may change without notice.
The features of the portfolio are not fixed and may vary over time within the limits provided in the fund prospectus.


