Anthony Bailly
Head of European Equity

Head of European Equity

European Equities Portfolio Manager
Inflation data once again drew attention in November. Surprising on the downside, either in the United States (slowing to 7.7% from 8.2% the previous month) and in the Eurozone with the first drop in 16 months (from 10.6% in October to 10% in November)1 , they fuelled the narrative of the Fed's pivot (whose definition remains multifaceted); and caused the markets’ October bullishness to spill over into November. In euros and with dividends reinvested, the MSCI World gained 2.6% in November, while the S&P 500 rose by 1.2%. However, it was the Eurostoxx, with dividends reinvested, that stood out, with the second highest monthly increase of the year, and a rise of +8.1%2.
In the United States, the Fed raised its key rates by 75 basis points (bps) for the fourth consecutive time, bringing them to a range of 4.0 to 4.25%1. However, in reaction to the worsening of some leading indicators (including the manufacturing PMI3 and ISM4 and the Conference Board consumer confidence index), Jerome Powell hinted at a slowdown in future rate hikes (which may be a first definition of the so-called pivot). However, recent solid job figures (+263,000 in November)5 won’t make it any easier for him to fight inflation.
In Europe, economic activity data came in more resilient than expected, including composite PMI figures that were up slightly (from 47.3 to 47.8), or even the rebound of the IFO6 and ZEW7 indices in Germany. This led the European Commission to revise its 2022 growth forecasts upward (to 3.2% from 2.7%), while its 2023 forecasts still point to a marked slowdown (at +0.3%).
In China, economic activity figures came in below forecasts (with retail sales down by 0.5%, a slowdown in manufacturing output, and a pullback in manufacturing and non-manufacturing PMIs)1. All this confirmed an economic slowdown that is shedding light on the difficulties caused by China’s zero-Covid policy. Late in the month, the markets’ zeroed in on hopes of reopening, hopes that were driven by some signs of easing of restrictions and protest demonstrations by the Chinese people.
Interest rates echoed inflation data, with a 44 bps decline in the US 10-year yield (-30 bps in real rates), and a 21 bps pullback in the Bund8 (-14 bps in real rates).
Supported by a season of better-than-expected earnings releases, which limited downward revisions to earnings per share (EPS), the European market rerated9 ; with a P/E10 of the Eurostoxx reinvested dividends rising to 12.2x from 11.4x the previous month. This shift was seen both for the Growth style, whose P/E rose from 18.7x to 19.8x, and for value11 stocks, from 7,7x to 8.4x, but P/E are still close to their all-time lows12. The valuation premium of Growth over Value thus remained, at the end of November, on a historically high premium of 135%; while German real rates have experienced, over the year 2022, a historic rise of more than 165 bps.
In a context of easing interest rates, this market increase has been particularly beneficial Growth sectors, with Consumer Goods (+15.4%) and Technology (+14.5%) ending as the best sectors for the month. While Growth style gained 9.9% in November, Value style did not disappoint, with an increase of 7.2%13. Since the beginning of the year in the Eurozone, the outperformance of Value over Growth thus remains significant, at +9.0%, with a Value index that is now down by only -3.5% (compared to -12.5% for the Growth index)14.
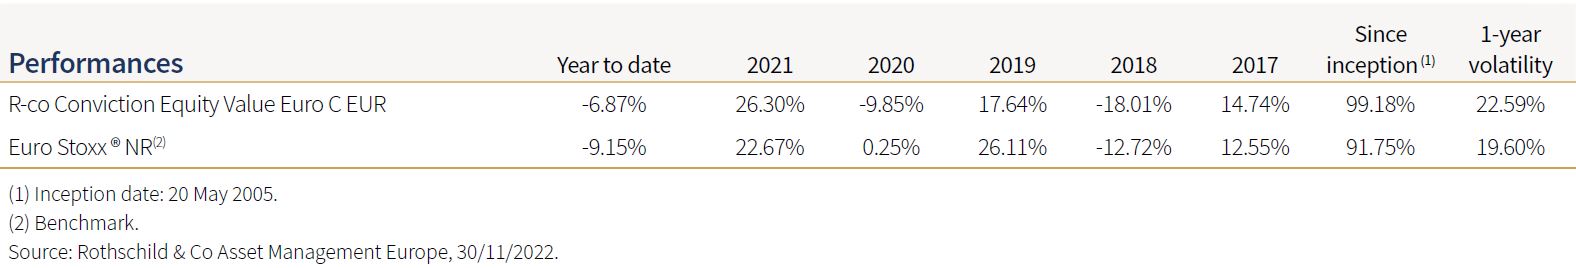
R-co Conviction Equity Value Euro performed in line with Value stocks in November (+7.3%)14, raising its year-to-date outperformance vs. its benchmark15 to +2.3%14. The fund's slight underperformance over the month compared with its benchmark (-0.8%) can be explained exclusively by its under-exposure to the two best sectors of the month: consumer goods and technology (see previous paragraph). While the selection effect had almost no impact on the fund's monthly performance, we would nevertheless note among our convictions the strong rebound of Alstom (+19.2%) and the good progress of BNP Paribas (+12.5%)14, which were nevertheless offset by the underperformance of more defensive stocks such as Sanofi (-1.0%) and Danone (-0.6%).
The peak of inflation, now confirmed in the US and rather earlier than expected in Europe continued to drive investors’ hopes. As a result, the market rally since mid-October has been driven mainly by cyclical stocks, whose discount vs. defensives had hit an all-time low late last summer14, as we had noted in our previous publications. This trend was also driven by a strong Q3 2022 reporting season, more mixed soft data16, all of which lends credibility to a scenario of moderate decline in activity in Europe.
Against this backdrop, we continued to raise our weighting of cyclical stocks in the portfolio, which reduced the weighting of the defensive pillar from 28% at end-September to 25% at end-November. This increased weighting resulted in part from the outperformance of cyclical stocks but was accentuated by several switches. For example, we raised our weightings of certain cyclical stocks that had been hit hard on the year to date (Faurecia: -60%; ProSieben: -34%; and Siemens: -12%), and took profits on some stocks that had outperformed (Deutsche Telekom: +22%; CaixaBank: +55%, TechnipEnergies: +18%, and EDP: -3%).
2023 EPS forecasts still look too high, with growth put at +7.6% (excluding commodities and energy)17. This is still overly optimistic when set against our moderate recession scenario. To further this pro-cyclical movement, we will wait for further progress on downward earnings revisions. Other factors could also help, including the continued reopening of China and a de-escalation on the Russian-Ukrainian front.
We have stuck to our marked overweighting of the banking sector, whose releases once again surprised on the upside and whose 2022 EPS forecasts have been revised upward by more than 18% on the year to date18. These revisions, driven by higher interest rates, are likely to continue in the years to come via repricing19 of loans on bank balance sheets. Hence, while the sector continues to be priced at near its lows, we still believe that higher interest rates will more than offset the earnings impact of the macroeconomic slowdown, as the coming rise in the cost of risk could be mostly absorbed by write-backs of Covid-19 provisions that are still on bank balance sheets.
Completed on 7 December 2022