
Anthony Bailly
Head of European Equity

Head of European Equity

European Equities Portfolio Manager
Financial markets rallied strongly in October, particularly in the second half of the month, as investors feared they would miss the pivotal shift in central banks rate hikes policy. In euros and with dividends reinvested, the MSCI World gained 6.1%, the S&P 500 gained, 7.0% and the Euro Stoxx outperformed with a rise of 8.0%(1).
Inflation remains the key concern. Financial markets continue to focus particularly on the US data, showing on the one hand, that CPI is slowing less quickly than expected, at 8.2% in October(1), that core inflation continues to accelerate, and that the US job market remains strong; and on the other hand, deteriorating leading indicators and a housing market that continues to weaken as a result of the Fed’s monetary policy tightening. The US central bank’s statements remained aggressive, leaving little hope for an increase of less than 75 basis points (bps), which finally materialized in early November.
In Europe, the ECB unsurprisingly decided to raise its key rates by another 75 bps, with the statement reminding us that further rate hikes are to come. Inflation figures in Europe were up again to 10.7% vs. 10% the previous month(2). Eurozone PMI(3) figures (for October) came in below forecasts, with the composite index slipping from 48.1 to 47.3(4), reinforcing the assumption of a recession in Q4. Good news included lower gas prices and full stocks ahead of the winter season. Finally, on the political side, Giorgia Meloni became Prime Minister of Italy and was cautious in her first speeches on Italy’s position in the European Union and on budgetary policy. A first approach that has so far reassured the markets.
And in China, the major element of this month of October was the 20th Congress of the Chinese Communist Party. Unsurprisingly, Xi Jinping was re-elected to a five-year term ending in 2027. On the economic front, GDP growth accelerated and production data also rose. However, consumption and industrial confidence (PMI index) turned out to be weaker than expected(1).
While the impact of these developments has been limited on nominal rates, which rose slightly on the month on both sides of the Atlantic (+3 bps for the Bund(5) and +22 bps for the US 10-year yield(1)), real rates pulled back after the steep rise in the previous month (-22 bps for the real 10-year Bund and -14 bps for the real US 10-year yield(1)).
And, lastly, prior to the results season, there were about 40 profit warnings(6), due to the inflationary environment, which has driven up costs and driven down consumer demand. Despite a start to the earnings season generally in line with expectations, management comments have increasingly raised the possibility of weaker demand in 2023. This has led analysts to begin a process of downward revision of earnings per share, even if these revisions remain modest at this stage.
The market rally was driven by Value, which outperformed Growth by 4.4% on the month(7), bringing its year-to-date outperformance to 10.3%(8). Value’s outperformance was driven, in turn, by the rally in its cyclical component. The top-performing sectors included Leisure & Travel (+16.5%), Energy (+13.1%), Capital Goods (+12.3%), Banks (+11.4%) and Construction (+10.3%)(8).
R-co Conviction Equity Value Euro took full advantage of this rebound, rising 10.6% in October(9) and outperforming its benchmark(10) by 2.6%(8). This brings the fund’s year-to-date outperformance to 2.8%(8). The fund benefited from positive allocation effect, notably through its overweighting of the energy and banking sectors and its underweighting on personal & household goods. Most of the fund’s outperformance over the month was driven by good stock-picking, with strong rallies in stocks that had been bid down in the previous month, including cyclicals (Faurecia and Alstom) and energy stocks (ENI and TotalEnergies).
Three elements still seem essential to us to follow closely before increasing the weight of cyclical stocks :
1. Whether inflation has peaked ;
2. Whether soft data(11) will continue to worsen ;
3. Whether downward revisions will begin in 2023 EPS forecasts.
We believe that in each of these factors we are approaching a turning point that could be interpreted by investors (who are currently steeply underinvested) as an opportunity to return to the equity markets. Rumors of the zero-Covid policy in China, and a particularly mild October in Europe, which allows us to enter the winter with full gas stocks, are other reassuring elements for investors.
In this context, the marked underperformance of cyclicals relative to defensives since the beginning of the year has led us to marginally strengthen our positions in the stocks that we believe are most likely to benefit from a market rebound. For example, we added to our exposure to automakers (Mercedes and Stellantis), chemicals (BASF), and construction (Saint-Gobain). Among the banking sector, we also strengthened our position in Société Générale prior to its earnings release. We reduced our position to Deutsche Telekom, which has performed very well within the sector since we expanded our position in June, and to Technip Energies, which which benefited from the good performance of the energy sector. If the above-mentioned indicators continue to move in a positive direction, we will gradually continue to strengthen the cyclical pillar of the portfolio in the coming weeks and months.
There was no fundamental change in the portfolio’s positioning in October. We are sticking to our strong convictions on the banking and energy sectors. Concerning energy, the results confirmed the strong cashflow generation, which is not reflected in the in the valuation of oil companies. Banking sector publications also confirmed the very positive impact of the rise in interest rates, as well as the impact of the macroeconomic deterioration on the level of provisions, which has enabled the sector to rebound in an environment where current valuations are close to historic lows.
Completed on 7 November 2022
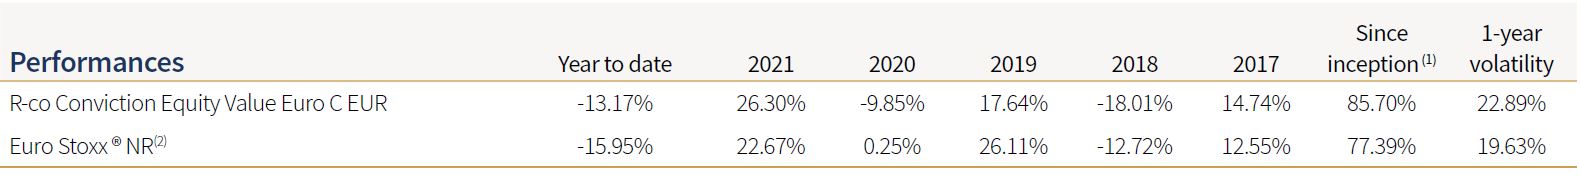
(1) Inception date: 20 May 2005.
(2) Benchmark.
Source: Rothschild & Co Asset Management Europe, 31 October 2022.


