
 |
 |
|
|
Yoann Ignatiew |
Charles-Edouard Bilbault |
|
|
Co-fund manager of R-co Valor & R-co Valor Balanced |
Co-fund manager of R-co Valor |
|
The first quarter of 2020 was unquestionably marked by an unprecedented external shock: the COVID-19 crisis. This health crisis, quite different from the financial crisis of 2008, led to an unprecedented collapse of global equity markets in an extremely short period of time. The S&P500 fell -34% in just over a month, while the Eurostoxx 50 collapsed -38% in an even shorter period of time.
Based on their experience from 2008, the various Central Banks and governments were quick to react, on a massive scale. Despite a certain lack of coordination, a series of measures were taken with a common goal to limit the impact of this crisis on their economies in the short term, “Whatever it takes”.
The central banks’ response was particularly swift, with the Fed cutting rates by 50 basis points as early as March 3. All main central banks subsequently followed suit, adjusting their rates to around 0%. At the same time, unconventional interventions were deployed, sometimes going beyond what had been done in 2008. The Fed added certain high-yield securities to the list of assets eligible within its purchase programme; as of April 8, the size of its balance sheet stood at USD 6044 billion, or around 28% of the country’s GDP. In Europe, a EUR 750 billion contingency plan called the “Pandemic Emergency Purchase Program” (or EPPP) was launched in mid-March. Since then, agreement in principle has been reached on the creation of a €1000 billion emergency fund to support the post-crisis recovery. The Bank of Japan (BoJ), in addition to intervening in the equity markets for several years,this week committed to buying unlimited amounts of government bonds. The measures taken by the various central banks have notably had the effect of providing liquidity to the money and bond markets. At the same time, governments are using a wide variety of tools to support both businesses and households. The measures vary from country to country. In France, measures include part-time work and tax deferral for companies. In the United States, the recovery plan implemented to date represents 11% of GDP and is aimed at preventing a cascade of corporate bankruptcies. At the household level, paychecks have been offered directly to individuals. As far as China is concerned, the government has in the past shown support towards its economy during the “Trade War” episode, so we can reasonably expect a stimulus plan in the infrastructure sector.
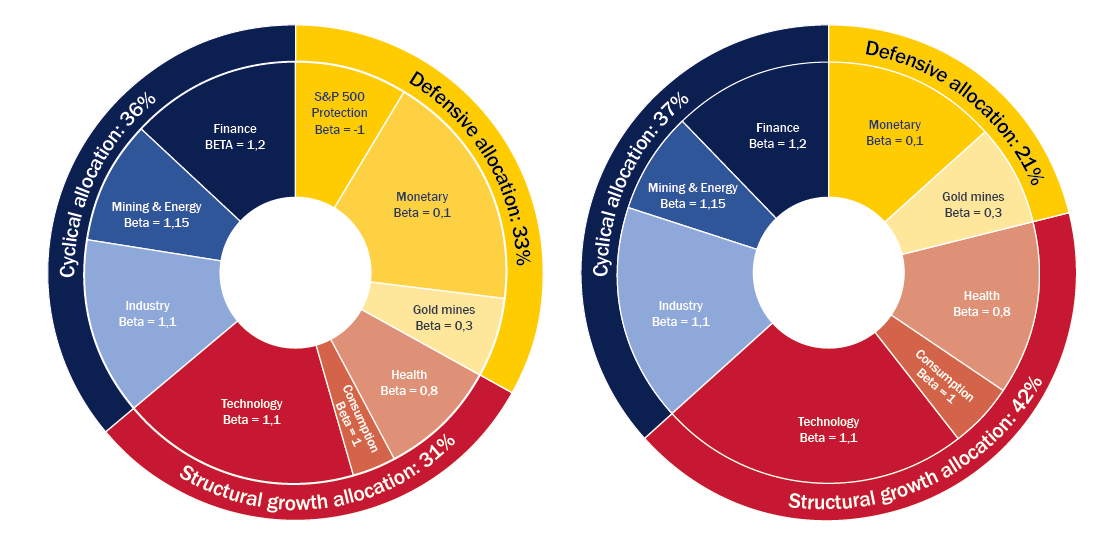
Within the R-co Valor portfolio, a reduction in risk had been initiated throughout 2019. As a result, at the beginning of 2020, the fund was positioned rather conservatively with a net equity exposure at 70%, the lowest level in 12 years.
This positioning allowed us to gradually rebuild risk throughout the correction to reach an exposure of 89% at the end of March. This was done in various ways: the sale in three steps of our short S&P 500 futures hedges, the initiation of new lines, and the strengthening of certain securities in the portfolio.
The policies of lowering key interest rates and the distortion of central bank balance sheets by monetary creation seem to offer a solid ground for a rebound in gold prices. Gold miners are among the positions strengthened during the correction. The sector will probably be one of the very few that can achieve both earnings and free cash flow growth. Exposure to “structural growth” stocks has also been increased: the technology sector, linked in particular to the Asian consumerism, but also the healthcare sector, one of the winners in the first quarter of 2020. With regards to new positions, cyclical stocks were favored, notably with the purchase of securities such as Airbus and ABB. The rationale of these investments is to position the fund for a recovery. Indeed, historically, cyclical stocks show a clear outperformance after a market correction. What can we expect for the rest of the year?
The economic recovery is unlikely to be “V” shaped. China, ahead of Europe and the United States, has gradually resumed its activities, but the recovery is taking place in a scattered order, the pace being less intense than before the crisis. Since the end of March, and after the rebound, (+28% in less than a month for the S&P 500) profit-taking has been taking place on some stocks that have performed strongly. Gilead Sciences in the healthcare sector or Vipshop in Chinese technology are examples of this. As a result, the fund’s equity exposure fell to 84%. The lack of visibility in the short term and the strong rally in some stocks prompted us to take some profits. Despite these uncertainties, we remain convinced that the most attractive asset class remains equities. The economic recovery will be gradual and will probably be supported unconditionally by governments and central banks.
The fund’s exposure and allocation will evolve based on opportunities, but in a disciplined manner, while maintaining the reactivity that characterizes the fund.
R-co Valor: The allocation is based on three distinct pillars
R-co Valor: Thematic and geographical breakdown of the portfolio
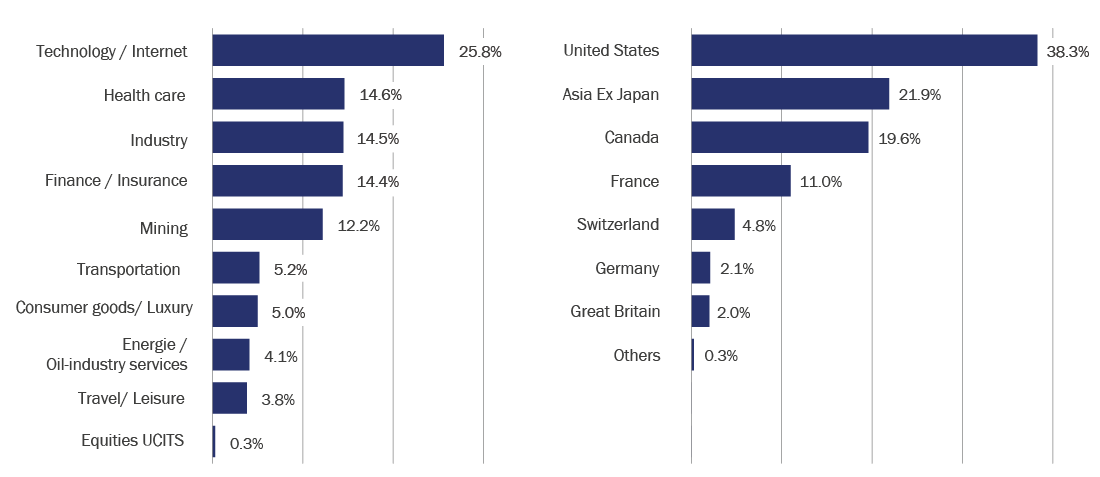
Source: Rothschild & Co Asset Management Europe, 31/03/2020
R-co Valor: Portfolio's top 10 holdings
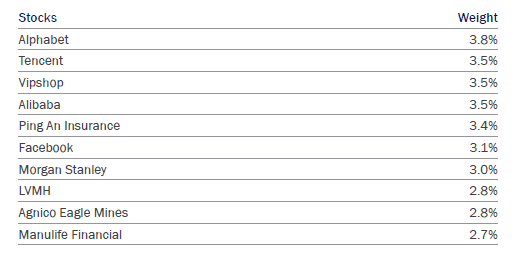
Source: Rothschild & Co Asset Management Europe, 31/03/2020
The features of the portfolio are not fixed and may vary over time.


