
Yoann Ignatiew
General Partner, Head of International Equity and Diversified


General Partner, Head of International Equity and Diversified

Global Equities Portfolio Manager
The last quarter of the year was influenced by a succession of market-friendly announcements: the end of electoral uncertainty in the United States, the development of effective vaccines against Covid-19, the conclusion of the “Brexit” saga, etc. In the process, some equity indices have reached record highs, such as the S&P 500, which returned nearly 12% in the quarter [1].
The macroeconomic picture remains mixed. The recovery that began in the third quarter was prematurely slowed down by the resurgence of infections, leading to additional restrictive measures in Europe and the United States. Symptoms of this dichotomy can be identified in the Manufacturing PMI [2] in Europe which expanded to 55, while the PMI for the service sector PMI fell significantly to 46.
In the United States, the declining unemployment rate, currently at 6.7% [3], actually hides large disparities within the population. It also excludes from the statistics any individual no longer actively seeking employment. For its part, China seems to be emerging from this pandemic standing tall, showing GDP growth of 6.5% in the fourth quarter and a trade balance reaching a record global surplus of 535 billion dollars [4].
Markets seem to be moving along, supported by rather buoyant macroeconomic figures, particularly accommodating central banks, and significant stimulus plans. Three situations could however become headwinds:
The horizon has nevertheless brightened up at the end of the year, fuelling hopes for a return to normality in 2021. With the pandemic under control and pent-up demand built over a year, the economic recovery could prove solid in the coming months.
[1] Source: Bloomberg, 21/12/2021.
[2] The Purchasing Managers’ Index is an indicator that measures the level of trust purchasing managers have in a given sector. If it is above 50, it shows that the sector is expanding, and below 50, that the sector is contracting. .
[3] Source: Bureau of Labor Statistics, December 2020.
[4] Brèves hebdomadaires du SER de Pékin, 01/02/2021.
Driven by a procyclical reallocation of equity markets, R-co Valor benefited from the performance of its industrial, financial and commodity allocations in the fourth quarter. Exposure to equities increased marginally since the end of September, from 83% to 84% at the end of December.
Profits were taken strategically as equity markets recovered. Some cyclical stocks were trimmed and the allocation to the automotive sector was completely sold with the exits of equipment manufacturer Magna International and Chinese manufacturer Great Wall Motor. In parallel, stocks with a more defensive profile, in particular those in the health and gold mining sectors, were reinforced. We also added some stocks in the tech sector at the margin following a correction at the end of the year, providing attractive entry points. French rail group Alstom was initiated over the period within industrials, which is a key player in sustainable mobility. Geographic exposure shifted slightly in favour of Europe, reaching a 25% weight within the equity portfolio at the end of December. North America and China represented 58% and 17%, respectively.
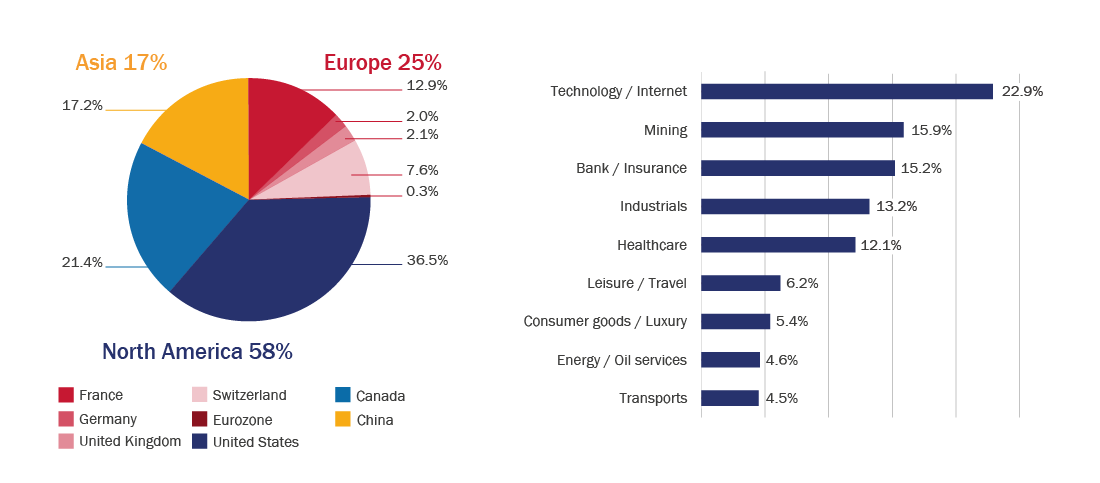
Source : Rothschild & Co Asset Management Europe, 31/12/2020.
The features of the portfolio are not fixed and may vary over time within the limits provided in the fund prospectus.


