
Yoann Ignatiew et Charles-Edouard Bilbault
Co-Fund Managers of the fund R-co Valor
The second quarter of 2019 was characterized by profit taking and reducing risk within the portfolio. As a result, its current equity allocation is at its lowest level in 10 years.
During the quarter, rail transport was the sector most affected by the risk reduction. We gradually reduced our exposure to Canadian Pacific Railway and fully liquidated our position on Canadian National Railway. The valuation levels of the sector no longer seem justified, in particular given the dynamic of rail traffic over the past two months.
Other reductions include LVMH in the luxury sector, and Capgemini following the announcement of a takeover bid on Altran. Among more marginal trims, still with a profit-taking mindset, we continued to decrease our positions in Honeywell, in Apple because of its exposure to the China-US trade war, as well as in Facebook given the rebound in the stock and uncertainties weighing on the environment in which the company operates.
The main shift, which occurred between late April and early May, was the implementation of hedges within the portfolio via S&P 500 futures contracts, representing approximately 10% of our equity allocation. These transactions carried out in two stages in a relatively short period of time, were based on the willingness to adopt a more defensive and reactive stance towards equity markets.
On the other hand, we finished building our position on Agnico-Eagle in the gold mining sector in early May, benefitting from the subsequent gold price appreciation. The last significant shift at the end of June was directly linked to the liquidation of Canadian National Railway, whose proceeds were reinvested in Citigroup, Capital One and Morgan Stanley shortly before the stress tests. Finally, we slightly strengthened Canadian National Resources in the energy sector. These movements increased our allocation to the financial sector while decreasing our exposure to the more cyclical ones.
Given the current valuation levels of equities, the situation is proving complex to assess. Equities are still trending higher, supported by Central Banks easing monetary policies, despite several signals of economic growth slowing down and rather negative earnings forecasts for the second quarter, combined with a very defensive positioning from investors.
At the end of June, our equity exposure stood at 71.5% net of futures contracts, the balance being invested in cash. Considering our aggressive equity allocation at the end of 2018, the lack of visibility coupled with the rise in valuations over the past six months is pushing us to limit our risk exposure and explains our lowest allocation to the asset class in 10 years.
R-co Valor: Portfolio’s geographical and thematic breakdown as of June 2019
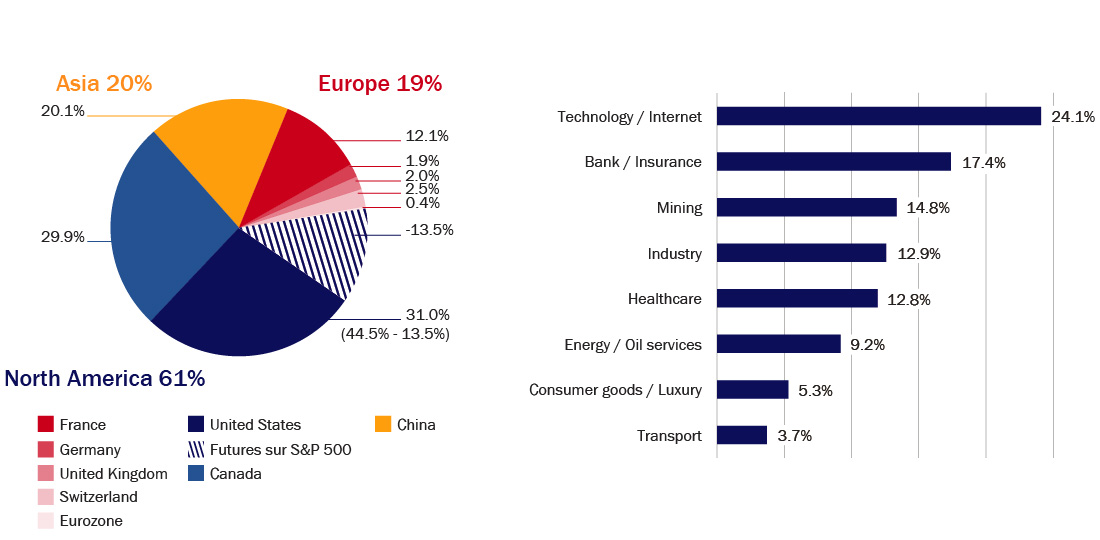
Source: Rothschild & Co Asset Management Europe, 28/06/2019
The features of the portfolio are not fixed and may vary over time.


