
Yoann Ignatiew et Charles-Edouard Bilbault
Co-Fund Managers of the fund R-co Valor
The latest developments in the Sino-US trade war have partially allayed the risk of a recession that emerged at the end of 2018, and the slowdown in growth is gradually beginning to show signs of a reversal, particularly in China.
Going into this year, China, the driving force of global growth, is benefiting from the solid performance of its economy combined with the initial impact of the stimulus measures initiated by the authorities in early 2019. Although this still needs to be confirmed, macroeconomic indicators point to a more favourable situation than expected, especially with regard to the rest of the world. In the United States, the race for the Democratic nomination is underway and the polls are already being closely monitored by market operators. Finally, at a global level, the dichotomy between the manufacturing and services confidence indices persist.
In Q4 2019, the technology sector was the main contributor to the fund’s performance, primarily driven by stocks such as Vipshop and Alibaba. Overall, Internet-linked Chinese stocks listed in the United States showed a remarkable performance following, in particular, the dissipation of some of the uncertainties generated by the Sino-US trade war. The share of e-commerce continues to grow in China and sales set new records in the latest promotional periods.
In the United States, the recent drop in the polls of Elizabeth Warren, the Democratic candidate who is particularly critical of the monopolistic status of large American “tech” companies, has been beneficial to Facebook and Alphabet. These two stocks pursued their progression that started right from the beginning of the year. In this context, our main shifts concerned the sale of Apple, as well as several reductions in Vipshop, in order to reduce the risks linked to these positions and to take profits on stocks that had substantially contributed.
US financials also delivered strong gains in the quarter. The less favourable polls for candidate Warren, and above all, the slight steepening of the yield curve, were particularly beneficial to them. Indeed, after three consecutive rate cuts, the Fed is expected to maintain the status quo. Moreover, the election period offers more visibility as these circumstances impose a certain neutrality, which is beneficial situation to the industry.
In addition, household consumption remains buoyant. Commercial events at the end of the year (Black Friday, Thanksgiving) resulted in a 7% increase in sales compared to the previous year. At the same time, credit card activities remain healthy with overall stable default rates. In this context, Citigroup, Capital One and Morgan Stanley were major contributors to the fund’s performance and we took advantage of this trend to take some profit.
Also benefiting from the easing of certain political risks, the healthcare sector posted a noteworthy performance over the period. We continued to strengthen our position in BioMarin. A profitable choice given the performance of the stock, particularly during the last fortnight of December. Other sub-sectors, such as pharmaceutical companies (AstraZeneca, Pfizer) and MedTech companies (Medtronic) benefited from similar dynamics.
As fears of recession risks subsided, the industrial sector emerged as a significant contributor to the SICAV’s performance over the quarter. The only shift made was a small top-up to Bombardier, benefitting from various market opportunities. For this highly volatile stock which is currently subject to a restructuring, 2020 will be a pivotal year, particularly in terms of free cash flow generation.
We were ultimately most active in the transport sector during the quarter. We consolidated Canadian Pacific Railway and Union Pacific Railway quite significantly to reach about 2% of the equity allocation for each position. Both of these stocks outperformed the rest of the sector overall, benefiting from an increase in transported volumes, the trade war’s improved outlook and the anticipated change in trade for 2020.
During the summer, the rise in value of the gold mining positions prompted us to take some of the profits, namely on Barrick Gold and Pretium Resources, before reinvesting in the latter at the end of the year. We aim to maintain a relatively stable exposure to this sector and the transactions carried out have only been very marginal. We are still positive about the gold market’s fundamentals. Outside of gold, Teck Resources suffered from the significant drop in coking coal prices during 2019, despite a recovery in copper prices. Ivanhoe Mines also benefited from higher palladium and platinum prices. We made no changes in this segment.
During this first quarter of 2020, we will continue paying particular attention to the negotiations between China and the United States around trade. “Phase 1” of a more comprehensive agreement has just been signed and we will be closely watching as “Phase 2” negotiations are launched. However, this first step has been widely anticipated by the markets in recent weeks and current valuation levels are proving to be particularly high over historical comparables. In an environment where interest rates remain lower than in previous economic cycles, equity risk premium remain particularly high, in turn inciting us to maintain our position in equity markets.
We will be closely monitoring the American elections, especially during the Democratic primaries. Once this first stage is over, the race for the White House is likely to shake up a number of sectors, and we will be careful to limit our risk exposure in such circumstances. Finally, we are closely monitoring Q4 2019 corporate earnings and management guidance for 2020. With an equity allocation slightly reduced during the quarter and currently adding up to approximately 70% of the portfolio’s net assets, we believe our positioning to be very reasonable given the environment in which we are operating, while providing us the flexibility to react opportunistically.
R-co Valor: Portfolio’s geographical and thematic breakdown
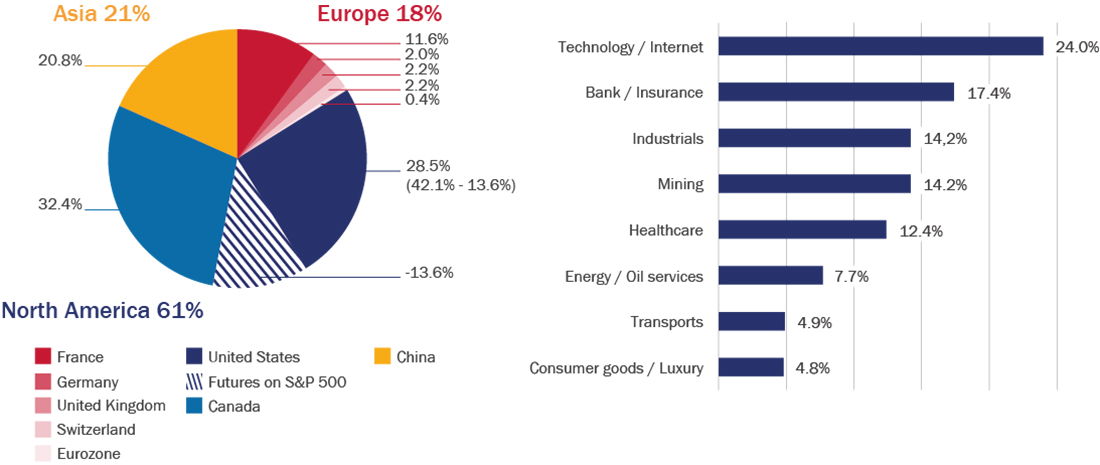
Source: Rothschild & Co Asset Management Europe, 31/12/2019
The features of the portfolio are not fixed and may vary over time.


