
 |
 |
|
|
Yoann Ignatiew |
Charles-Edouard Bilbault |
|
|
Co-fund manager of R-co Valor |
Co-fund manager of R-co Valor |
The global lockdown caused by the COVID-19 pandemic resulted in one of the fastest recessions in history. At the same time, the exceptional support measures from governments and central banks have turned the global economy on its head, making it possible to consider the second quarter of 2020 under the sign of market recovery.
The MSCI World All Countries, representing both developed and developing countries, regained, at the end of June, two-thirds of its losses from its lowest point. The index dropped by 34% between mid-February and early March. The economies are however restarting in dispersed order. China, ahead of Europe and the United States, has fully resumed its activities and could display a GDP growth of around 2% in 2020. The CSI 300 index of the main capitalisations of the Shanghai and Shenzhen stock exchanges posted resolutely positive performance since the beginning of the year (+16% taking into account the beginning of July).
In Europe, the PMI Composite stood at 48.5 in June, close to the threshold of 50, above which it would reflect growth in activity. As a reminder, in April, it was 13.5, its lowest level since the surveys were created in 1998. Even within Europe, divergences are emerging. The German equity market clearly outperformed its neighbours with a DAX index at -7.08% from January to end June, against -13.65% for the Euro Stoxx 50. This can be explained by several factors, including effective management of the epidemic in Germany, helped by a higher hospital capacity than in other countries, as well as by a younger affected population, an economy based on a mainly manufacturing structure, less impacted than the tourism, hotel or banking sectors; and lastly, unprecedented support measures implemented by the government.
In the United States, despite macroeconomic data marking a recovery and in particular the unemployment rate dropping to 11.1% after reaching almost 15% in May, the situation is extremely unstable with an uncontrolled outbreak of the epidemic. In fact, 40 of the 50 States are currently showing a surge in new cases.
R-co Valor
Within R-co Valor’s portfolio, exposure to equities has gradually decreased since the end of March, from 89% to 82% at the end of June. A profit-taking strategy was implemented throughout the upturn of the indices. Chinese technology stocks, posting positive performances in absolute and relative terms, were capped, with Vipshop, an e-commerce company, in the lead. In the healthcare sector, Gilead Sciences was significantly reduced, following the strong performance of the share upon the approval of its COVID-19 treatment, Remdesivir. However, the fund’s exposure to the sector remains stable.
Profit-taking was also recorded in gold mining, with the sector benefiting from renewed interest from generalist investors. Gold’s safe-haven status coupled with real interest rates in negative territory make it an attractive investment again.
With US elections around the corner and the risk of a second wave of contamination with possibly a new lockdown, volatility is likely to persist in the markets. As such Joe Biden is currently ahead by more than 10 points in the polls compared to his rival, incumbent President Donald Trump. The Democrats’ takeover of the Senate in addition to the House of Representatives would mark a real turning point in American political landscape.
In addition, the corporate earnings season starting in mid-July will be a trend indicator; investors will be looking at the ability of companies to plan for the end of the year. Despite these uncertainties, we remain convinced that equities remain the preferable option. A persistently low interest rate environment combined with the colossal level of available liquidity ($4.7 trillion worldwide) will be significant supports for this asset class once investors overcome their risk aversion.
R-co Valor : Portfolio’s geographical and thematic breakdown
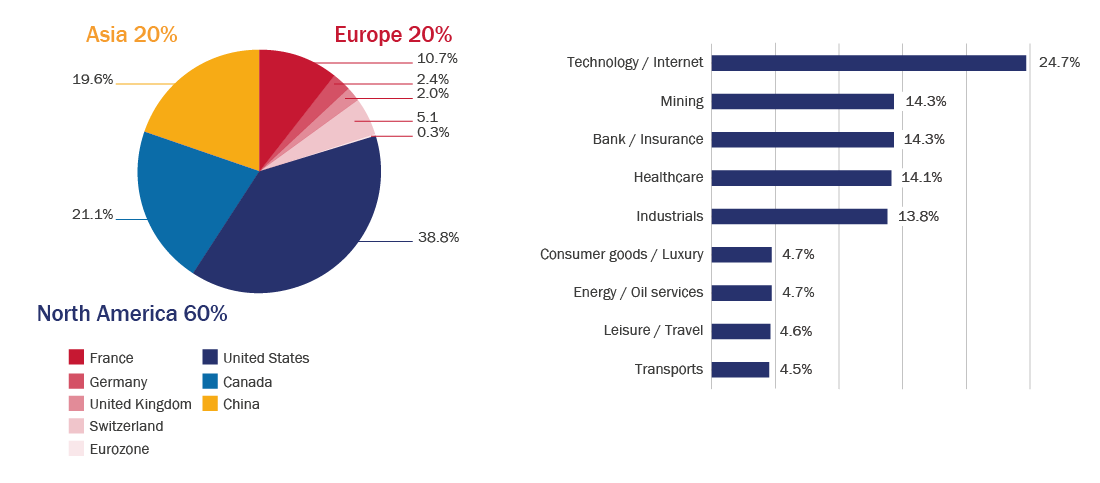
Source: Rothschild & Co Asset Management Europe, 30/06/2020.
The features of the portfolio are not fixed and may vary over time.
Find all the information available on the fund: R-co Valor
1 Source: Bond Radar, S&P LCD, Morgan Stanley Research, July 2020.


