
Kristell Agaësse
Head of High Yield & Convertible Bonds

Head of High Yield & Convertible Bonds
Following a disastrous first half of the year in the fixed income markets, a wide window of opportunity has opened up for reinvesting in mature funds.
The combined impact of the inflationary shock, following a massive budgetary shock, and exacerbated by the war in Ukraine, in a context where production lines have seized up due to China's "zero Covid" policy, are pushing central banks to drastically tighten their monetary policies. The extent of the expectations of liquidity reduction led to a historic fall in the fixed-income markets, particularly in the High Yield segment[1]. At the end of June, its performance stood at -15%[2], and its yield jumped from 2.8% at the beginning of the year to over 7%[2].
Indeed, the resulting fears about economic growth are weighing on the asset class, as seen in the significant underperformance of the cyclical and financial sectors. This integration of the risk premium naturally leads to a significant increase in default rate expectations. They are now comparable to the March 2020 level. At 600 basis points, the iTraxx Xover CDS index implies a 38%[3] default rate in the high yield market over the next 5 years, well above the levels observed in the past, regardless of the economic environment.
We therefore believe that the number of defaults by high-yield issuers is likely to increase over the next two years, but the market has already anticipated this. What can be said with confidence is that a portfolio such as R-co Thematic Target 2026 HY, which offers a return of almost 10% over a 4-year maturity, is without doubt an investment window.
Indeed, even if uncertainties remain, it can be underlined that the High Yield pool has several supporting elements. A key supporting factor is likely to be the marked improvement in the fundamentals of issuers. They have been working on two major areas: reducing their cost structure after the Covid-19 crisis and reducing their debt levels. As a result, EBITDA[4] growth has accelerated to record levels and liquidity levels are more than sufficient to allow issuers to finance themselves over the next few years. During the period of low interest rates, issuers have been extremely proactive in refinancing their closest maturities, which protects them from short-term refinancing risk in these difficult market conditions. The primary High Yield market has indeed dried up since the beginning of the year, down sharply compared to the same period last year. However, the current pool remains sufficient for this average maturity of 2026.
EBITDA growth appears to have peaked in 4Q21, while net debt growth picked up
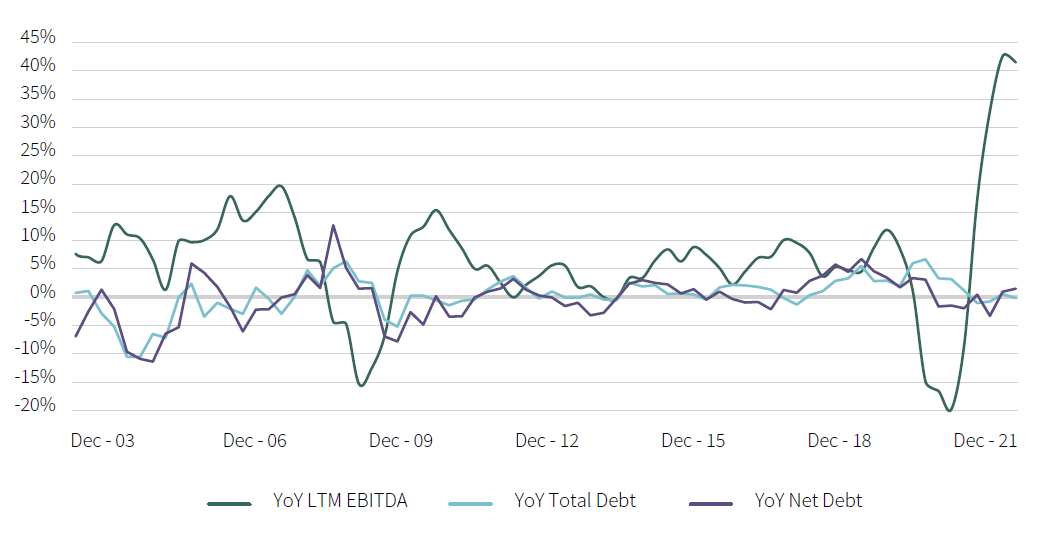
Source: Bloomberg, company data, Morgan Stanley Research – 4Q 2021.
In summary, the market environment describes an extreme situation that may turn out to be more resilient, thanks to a clear improvement in issuers' fundamentals since 2020.
R-co Thematic Target 2026 HY is an opportunity for investors to avoid focusing on the volatility of short-term financial markets and to think in terms of repayment at maturity and annualised yield. R-co Thematic Target 2026 HY is the 6th generation of Rothschild & Co Asset Management Europe's maturity fund, and invests in Euro-denominated high yield bonds, with a core portfolio of BB and B ratings. We apply an active, agile and disciplined management style, allowing us to seize opportunities and arbitrate, or even sell, if the risk of default becomes too significant. The management-analyst team is at the heart of the fund's management.
Main features of R-co Thematic Target 2026 HY ·
[1] High-yield bonds are issued by companies or governments with a high credit risk. Their financial rating is below BBB- on the Standard & Poor’s scale.
[2]Source: Bloomberg, 30/06/2022
[3] Source: Morgan Stanley Research, Bloomberg, Moody’s - 18/07/2022.
[4] EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization). An indicator used to assess the profitability of a company's operating cycle, regardless of its investment or financing policy.
The figures quoted relate to the past months. Past performance is not a reliable indicator of future performance and is not constant over time.
Performance calculated in Euros and net of dividends reinvested.
The management team is subject to change.
The characteristics/objectives/strategies mentioned above are indicative and subject to change without notice.
This analysis is only valid at the time of writing.
The geographical and sector allocations and distributions are not fixed and may change over time within the limits of the fund's prospectus.
The above information does not constitute investment advice or a recommendation to invest.
The information contained herein does not constitute investment advice, tax advice, a recommendation or investment advice from Rothschild & Co Asset Management Europe.


