
Anthony Bailly
Head of European Equity

Head of European Equity

European Equities Portfolio Manager
After extending their July bull run (+2.5% from 29 July to 16 August 2022 by the EuroStoxx with dividends reinvested(1)), the markets pared their gains prior to, and during, the Jackson Hole symposium of late August (-7.3% from 16 August 2022 to 31 August 2022 by the EuroStoxx with dividends reinvested(2)). The EuroStoxx with dividends reinvested ultimately ended August down by -5.0% on the month, while the S&P 500 lost -4.1%(2) (in dollars). While the summer rally(3) had been driven by hopes of a Fed pivot, Jerome Powell and his peers served notice that they would continue to tighten monetary policies, thus focusing investors on their top priority at the moment, which is price stability and, hence, the fight against inflation.
Inflation concerns were especially pronounced in Europe, where the energy crisis moved up to a new level. Tensions were exacerbated and gas and electricity prices set new records after a historic drought in Europe and the announcement of a new suspension of Russian gas exports via Nordstream 1. The megawatt-hour hit €1000 in Germany(4), while European gas prices hovered around €350/MWh(4). In addition to being prohibitive and having a direct impact on the economy, high energy prices point to steeper inflation both in Europe and the rest of the world, while postponing peak inflation in Europe. And, indeed, the euro zone CPI set a new record at 9.1% (vs. 8.9% the previous month(2)), driven by prices of food, industrial goods (ex energy) and services, thus suggesting a troubling dissemination of higher prices throughout the economy. The euro zone PMI(5) composite continued to worsen, to 48.9 (vs. 49.4 the previous month(2)), with both services and manufacturing components under the 50 threshold.
In the US, the news was more reassuring, with an robust job market (528k jobs created vs. 250k forecast(3)), an upward revision of second-quarter GDP (from -0.9% quarter-on-quarter to -0.6%(2)), and weaker, and below-forecast inflation (at 8.5% in July vs. 9.1% in June and 8.7% forecast(2)) that may have therefore already peaked. Meanwhile, ISM manufacturing and non-manufacturing indices came out at 52.8 and 56.7, respectively, vs. 52.1 and 53.92 forecast, thus confirming the resiliency of the US economy, where the real-estate market alone showed true signs of weakening (with housing starts down by 9.6% and new home sales down by 12.6%(6)).
A recovery is taking time to materialise in China, as the zero-Covid policy continues to restrict mobility, and as the drought is causing electricity shortages and penalising regions that are key to Chinese output. As a result, macroeconomic data worsened (industrial output up by 3.8% vs. 3.9% the previous month, retail sales up by 2.7% vs. 3.1%, and investments up by 5.7% vs. 6.1%)(7), as did the PMI Caixin Manufacturing index (from 51.7 on 1 July to 50.4 on 1 August and 49.5 on 1 September)(8). And yet, the authorities had no qualms about priming the pump, with the PBoC(9), cutting mortgage lending rates for the second time this year and announcements of support from the Chinese State Council totalling 800 billion yuan (120 billion dollars).
Bond yields moved back up aggressively after dipping in July. The 10-year US yield ended the month up by 55 basis points (bp) at 3.2%(3), while the Bund(10) rose by 72bp, reaching 1.53% by 31 August 2022. These increases were driven almost exclusively by higher real rates and benefited value stocks11, which lost just 3% on the month, while growth stocks(12) were down by 7.2%, thus lowering value’s outperformance vs. growth to +6.6%(7) on the year to date.
On the macroeconomic level, companies continued to report excellent second-quarter numbers, particularly in Europe. This led to new upward revisions of forecasts of earnings per share (EPS), which are now put at +18.8% for the STOXX Europe 600 (+5.7% ex commodities) and +2.9% pour 2023 (+9.7% ex commodities)(13). Although guidance was slightly less upbeat, optimism is still the byword, particularly on the strength of demand and even margins, which is at odds with the weakening of soft and hard macroeconomic data(14) in Europe.
In this challenging market environment, R-co Conviction Equity Value Euro (-3.1%(7) on the month of August) outperformed its benchmark(15) by +1.9% (+1.2% on the year to date)(7), due mainly to allocation, thus reflecting the strong, and oft-repeated, correlation between higher interest rates and outperformance by value stocks. Exactly unlike the previous month, the fund was driven by both the outperformance of our main weightings (banks and energy) and the underperformance of one of our main underweightings (technology). Regarding stock-picking, note the very good performance of TechnipEnergies (+8.2%)(8), driven by its natural gas exposure, whereas Sanofi gave up all its year-to-date gains (-15.5% in August, and -5.2% YTD)(8), due to legal uncertainties surrounding its Zantac drug.
We chose during the second half of June to switch some exposure from cyclicals to defensives, due to the worsening macroeconomic data and the high level of uncertainties (the European energy crisis in particular). Since then, we have made no attempt to add to the portfolio’s cyclical weighting, due:
1. to soft data, which continue to worsen;
2. to inflation, which is persistent in Europe;
3. to the worsening of the energy crisis, considering, as we explained last month, that the summer rally was a false signal.
We are sticking to a relative cautious view of the macroeconomic environment for the weeks and months to come, based on the fact that uncertainties are trending upward as the summer draws to a close. That being said, the relative valuation of cyclical stocks vs. defensives has hit an all-time low, and, as a result, we are not raising the weighting of our defensive pillar. If PMIs continue to worsen and cyclical share prices are impacted once again, we may be investing once again in the hardest hit stocks.
We have nonetheless held on to two marked cyclical biases in the form of banking and energy stocks, for two reasons that apply to both sectors:
1. Valuation ratios are still at historical lows;
2. There is still significant potential for the coming quarters (via higher interest rates for banks and, for energy stocks, oil & gas prices that are likely to remain higher than the levels assumed in analysts’ models).
Meanwhile, we still believe that the energy sector, for once, offers defensive features in the current geopolitical context. The message sent out by OPEC in early September, in deciding to reduce its output for the first time in two years, reinforces our opinion.
Regarding adjustments to the portfolio, we bought into weakness on Sanofi to expand our position. With a 22 billion euros loss in capitalisation(16), the market had already priced in the worst-case scenario in civil damage payments. We sold down some financial and energy stocks (Axa +4.8%, Technip Energies +8.2%)(17) after their strong performance, to rebalance the defensive pillar, while overweighting international exposure via AB InBev. Lastly, we closed out our position in Telecom Italia, due to national political uncertainties and to its lack of geographical diversification, while investing in Deutsche Telekom, whose US exposure allowed us to better adjust our risk profile.
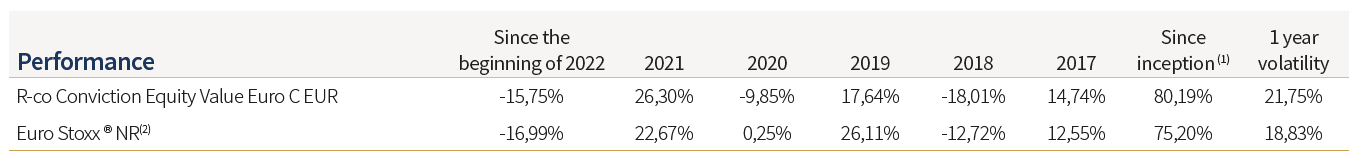 (1) Inception date: 20/05/2005.
Completed on 7 September 2022


